How do you calculate interest earned on a savings account? It's actually pretty simple. Find out how much interest $1000 will earn in a year.
How much interest will I get on $1,000 a year in a savings account?
If your savings account has an interest rate of 1%, you can earn $10 in interest for one year.
Reduce that interest rate to the national average of 0.07% and you would see $0.70 in interest for the year. You can't even buy a cup of coffee for that. Fortunately, some banks offer higher interest rates.
Unlock Expert Savings Tips!
Join our wealth-building community and get savvy savings tips straight to your inbox, every Tuesday.
How Much Interest You Will Earn on $1,000
Here is a table of how much interest $1,000 will earn in 1, 10, and 20 years at different interest rates:
| Rate | 1 Year | 10 Years | 20 Years |
|---|
| 0.00% | $1,000 | $1,000 | $1,000 |
|---|
| 0.25% | $1,003 | $1,025 | $1,051 |
|---|
| 0.50% | $1,005 | $1,051 | $1,105 |
|---|
| 0.75% | $1,008 | $1,078 | $1,161 |
|---|
| 1.00% | $1,010 | $1,105 | $1,220 |
|---|
| 1.25% | $1,013 | $1,132 | $1,282 |
|---|
| 1.50% | $1,015 | $1,161 | $1,347 |
|---|
| 1.75% | $1,018 | $1,189 | $1,415 |
|---|
| 2.00% | $1,020 | $1,219 | $1,486 |
|---|
| 2.25% | $1,023 | $1,249 | $1,561 |
|---|
| 2.50% | $1,025 | $1,280 | $1,639 |
|---|
| 2.75% | $1,028 | $1,312 | $1,720 |
|---|
| 3.00% | $1,030 | $1,344 | $1,806 |
|---|
| 3.25% | $1,033 | $1,377 | $1,896 |
|---|
| 3.50% | $1,035 | $1,411 | $1,990 |
|---|
| 3.75% | $1,038 | $1,445 | $2,088 |
|---|
| 4.00% | $1,040 | $1,480 | $2,191 |
|---|
| 4.25% | $1,043 | $1,516 | $2,299 |
|---|
| 4.50% | $1,045 | $1,553 | $2,412 |
|---|
| 4.75% | $1,048 | $1,591 | $2,530 |
|---|
| 5.00% | $1,050 | $1,629 | $2,653 |
|---|
| 5.25% | $1,053 | $1,668 | $2,783 |
|---|
| 5.50% | $1,055 | $1,708 | $2,918 |
|---|
| 5.75% | $1,058 | $1,749 | $3,059 |
|---|
| 6.00% | $1,060 | $1,791 | $3,207 |
|---|
| 6.25% | $1,063 | $1,834 | $3,362 |
|---|
| 6.50% | $1,065 | $1,877 | $3,524 |
|---|
| 6.75% | $1,068 | $1,922 | $3,693 |
|---|
| 7.00% | $1,070 | $1,967 | $3,870 |
|---|
| 7.25% | $1,073 | $2,014 | $4,055 |
|---|
| 7.50% | $1,075 | $2,061 | $4,248 |
|---|
| 7.75% | $1,078 | $2,109 | $4,450 |
|---|
| 8.00% | $1,080 | $2,159 | $4,661 |
|---|
| 8.25% | $1,083 | $2,209 | $4,882 |
|---|
| 8.50% | $1,085 | $2,261 | $5,112 |
|---|
| 8.75% | $1,088 | $2,314 | $5,353 |
|---|
| 9.00% | $1,090 | $2,367 | $5,604 |
|---|
| 9.25% | $1,093 | $2,422 | $5,867 |
|---|
| 9.50% | $1,095 | $2,478 | $6,142 |
|---|
| 9.75% | $1,098 | $2,535 | $6,428 |
|---|
| 10.00% | $1,100 | $2,594 | $6,727 |
|---|
| 10.25% | $1,103 | $2,653 | $7,040 |
|---|
| 10.50% | $1,105 | $2,714 | $7,366 |
|---|
| 10.75% | $1,108 | $2,776 | $7,707 |
|---|
| 11.00% | $1,110 | $2,839 | $8,062 |
|---|
| 11.25% | $1,113 | $2,904 | $8,433 |
|---|
| 11.50% | $1,115 | $2,970 | $8,821 |
|---|
| 11.75% | $1,118 | $3,037 | $9,225 |
|---|
| 12.00% | $1,120 | $3,106 | $9,646 |
|---|
| 12.25% | $1,123 | $3,176 | $10,086 |
|---|
| 12.50% | $1,125 | $3,247 | $10,545 |
|---|
| 12.75% | $1,128 | $3,320 | $11,024 |
|---|
| 13.00% | $1,130 | $3,395 | $11,523 |
|---|
| 13.25% | $1,133 | $3,470 | $12,044 |
|---|
| 13.50% | $1,135 | $3,548 | $12,587 |
|---|
| 13.75% | $1,138 | $3,627 | $13,153 |
|---|
| 14.00% | $1,140 | $3,707 | $13,743 |
|---|
| 14.25% | $1,143 | $3,789 | $14,359 |
|---|
| 14.50% | $1,145 | $3,873 | $15,001 |
|---|
| 14.75% | $1,148 | $3,958 | $15,669 |
|---|
| 15.00% | $1,150 | $4,046 | $16,367 |
|---|
How Much Interest Will You Earn?
Looking for a high-yield account? Check out these top options:
Interest on Savings Accounts
 |
| © CreditDonkey |
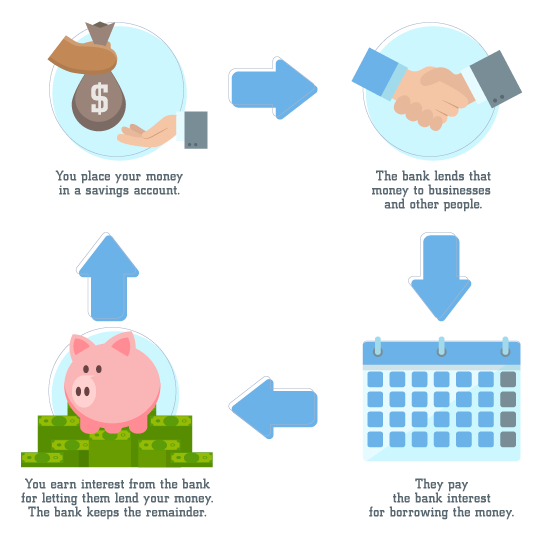
Borrowing money comes at a cost: this is called interest. When the time comes to pay the money back, the interest is paid back in addition to the original amount that was borrowed.
When you deposit your money into a savings account, the bank is essentially borrowing your money. The bank then loans your money to borrowers and, in return, it pays you interest for letting it use your money.
Member FDIC
With 6 month boost, you earn:
| Tier |
Boost APY |
| Balance over $5,000 |
4.25%* |
| Balance less than $5,000 |
0.75%* |
After boost is completed, you will continue to earn our best standard rates:
| Tier |
APY |
| Balance over $5,000 |
3.75%1 |
| Balance less than $5,000 |
0.25%1 |
- Needs to use promo code to qualify: Boost50
- Boost lasts 6 months over standard APY
- Tiered account
- $100 minimum account opening
- Member FDIC
- No Monthly Service fees
- No account opening fees
Expires 12/15/2026
DisclosuresPlatinum Savings is a tiered interest rate account. Interest is paid on the entire account balance based on the interest rate and APY in effect that day for the balance tier associated with the end-of-day account balance. APYs — Annual Percentage Yields are accurate as of January 9, 2026: 0.25% APY on balances of $0.01 to $4,999.99; 3.75% APY on balances of $5,000.00 or more. Interest Rates for the Platinum Savings account are variable and may change at any time without notice. The minimum to open a Platinum Savings account is $100.
This is a limited time offer available to New and Existing customers who meet the Platinum Savings APY Boost promotion criteria.
Accounts enrolled in the Platinum Savings Annual Percentage Yield (APY) Boost promotion will receive a 0.50% APY boost on the Platinum Savings current standard APY tiers for 6 months following the opening of a new account or when an existing Platinum Savings account is enrolled in the promotion. The Platinum Savings APY boost will be applied on account balances up to $9,999,999.00. Account balances above $9,999,999.00 will earn the standard APY. If the standard-published APY should change during the promotion period, the APY boost will move with it, offering an account APY above the standard rate.
The Promotion begins on September 29, 2026, and ends December 15, 2026. Customers enrolled in the promotion prior to the end date will receive the APY boost for the 6-month period outlined in the terms and conditions.
The promotion can end at any time without notice.
New CIT Bank Customers: This Platinum Savings APY Boost promotion offer is valid for New CIT Bank customers, who, at account opening, do not have a valid CIT Bank User ID (a "New Customer") or any open CIT Bank accounts provided that the following requirements are met:
- New customers must open a Platinum Savings account with a valid Promo Code, Boost50. The Platinum Savings APY Boost Promo Code will appear on the online account opening enrollment web page. The Promo Code must be used at the time of account opening. Accounts opened during the program period without the Promo Code are ineligible to receive the APY boost.
- The enrolled Platinum Savings account must be open to receive the APY boost during the promotional period.
CIT Bank Customers with an account prior to the promotion: This Platinum Savings APY Boost promotion is valid for a Primary account owner with an existing account with a CIT Bank User ID before the start of the promotion, provided that the following requirements are met:
- Customers without a Platinum Savings account open prior to the Promotion must open a new Platinum Savings account via the enrollment web page using Promo Code Boost50.
- Customers with a Platinum Savings account opened prior to the promotion may enroll their current Platinum Savings account into the Platinum Savings Boost promotion via the enrollment web page using Promo Code Boost50.
- Customers who are not the Primary account owner on a Platinum Savings account may open a new Platinum Savings account as the primary account owner via the enrollment web page using Promo Code Boost50.
- Accounts opened or enrolled during the program period without the Promo Code are ineligible to receive the APY boost.
There is a limit of one Platinum Savings APY Boost promotional offer per account and per Primary customer. If multiple Platinum Savings accounts are opened, only one account per primary account owner is eligible.
There is no minimum account balance requirement to participate in the Platinum Savings APY Boost promotion.
Additional Important Terms
- The Platinum Savings APY Boost promotion may not be combined with other promotions.
- Customers are ineligible to participate in the Platinum Savings APY Boost promotion if:
- They are earning an APY over the standard rate.
- They participated in a previous APY Boost promotion.
- They participated in a cash bonus promotion in the past 6 months.
- Custodial accounts and accounts in the name of a Trust are not eligible.
- This offer is non-transferable.
The value of Platinum Saving Boost will be reported as interest income on IRS Form 1099-INT for the calendar year in which it was paid. The recipient is responsible for any applicable taxes.
For complete list of account details and fees, see our Personal Account disclosures.
Elevate Your Savings Game
Ready to boost your savings? Don't miss out on exclusive deals and savings strategies with our newsletter, sent straight to your inbox.
How Is Interest Calculated?
The formula for calculating the interest you'll earn from a savings account is as follows:
I = P x R x T
Once you get a grasp of the following terms, it's simple to use:
- I = Interest. This is the amount of money paid to you by the bank.
- P = Principal. This represents the sum you deposited into your account.
- R = Rate. This is the annual interest rate offered by the bank.
- T = Time. Since we are considering an annual interest rate, time in this case is the number of years that has passed.
As an example, let's say that you deposit $1,000 into a savings account with an interest rate of 2.0%. If you wanted to figure out how much interest you will earn after one year, you would use the formula as follows:
I = $1,000 x 2% x 1 = $20
Your account balance at the end of the year would then be $1,020.
Member FDIC
- $100 minimum opening deposit
- No monthly maintenance fee
- Member FDIC
DisclosuresAPY — Annual Percentage Yield is accurate as of July 1, 2026. Interest Rates for the Savings Connect Account are variable and may change at any time without notice. The minimum to open a Savings Connect account is $100. Fees could reduce earnings on the account.
For complete list of account details and fees, see our Personal Account disclosures.
How Much Interest Does $10,000 Earn?
| Rate | 1 Year | 10 Years | 20 Years |
|---|
| 0.00% | $10,000 | $10,000 | $10,000 |
|---|
| 0.25% | $10,025 | $10,253 | $10,512 |
|---|
| 0.50% | $10,050 | $10,511 | $11,049 |
|---|
| 0.75% | $10,075 | $10,776 | $11,612 |
|---|
| 1.00% | $10,100 | $11,046 | $12,202 |
|---|
| 1.25% | $10,125 | $11,323 | $12,820 |
|---|
| 1.50% | $10,150 | $11,605 | $13,469 |
|---|
| 1.75% | $10,175 | $11,894 | $14,148 |
|---|
| 2.00% | $10,200 | $12,190 | $14,859 |
|---|
| 2.25% | $10,225 | $12,492 | $15,605 |
|---|
| 2.50% | $10,250 | $12,801 | $16,386 |
|---|
| 2.75% | $10,275 | $13,117 | $17,204 |
|---|
| 3.00% | $10,300 | $13,439 | $18,061 |
|---|
| 3.25% | $10,325 | $13,769 | $18,958 |
|---|
| 3.50% | $10,350 | $14,106 | $19,898 |
|---|
| 3.75% | $10,375 | $14,450 | $20,882 |
|---|
| 4.00% | $10,400 | $14,802 | $21,911 |
|---|
| 4.25% | $10,425 | $15,162 | $22,989 |
|---|
| 4.50% | $10,450 | $15,530 | $24,117 |
|---|
| 4.75% | $10,475 | $15,905 | $25,298 |
|---|
| 5.00% | $10,500 | $16,289 | $26,533 |
|---|
| 5.25% | $10,525 | $16,681 | $27,825 |
|---|
| 5.50% | $10,550 | $17,081 | $29,178 |
|---|
| 5.75% | $10,575 | $17,491 | $30,592 |
|---|
| 6.00% | $10,600 | $17,908 | $32,071 |
|---|
| 6.25% | $10,625 | $18,335 | $33,619 |
|---|
| 6.50% | $10,650 | $18,771 | $35,236 |
|---|
| 6.75% | $10,675 | $19,217 | $36,928 |
|---|
| 7.00% | $10,700 | $19,672 | $38,697 |
|---|
| 7.25% | $10,725 | $20,136 | $40,546 |
|---|
| 7.50% | $10,750 | $20,610 | $42,479 |
|---|
| 7.75% | $10,775 | $21,095 | $44,499 |
|---|
| 8.00% | $10,800 | $21,589 | $46,610 |
|---|
| 8.25% | $10,825 | $22,094 | $48,816 |
|---|
| 8.50% | $10,850 | $22,610 | $51,120 |
|---|
| 8.75% | $10,875 | $23,136 | $53,529 |
|---|
| 9.00% | $10,900 | $23,674 | $56,044 |
|---|
| 9.25% | $10,925 | $24,222 | $58,672 |
|---|
| 9.50% | $10,950 | $24,782 | $61,416 |
|---|
| 9.75% | $10,975 | $25,354 | $64,282 |
|---|
| 10.00% | $11,000 | $25,937 | $67,275 |
|---|
| 10.25% | $11,025 | $26,533 | $70,400 |
|---|
| 10.50% | $11,050 | $27,141 | $73,662 |
|---|
| 10.75% | $11,075 | $27,761 | $77,068 |
|---|
| 11.00% | $11,100 | $28,394 | $80,623 |
|---|
| 11.25% | $11,125 | $29,040 | $84,334 |
|---|
| 11.50% | $11,150 | $29,699 | $88,206 |
|---|
| 11.75% | $11,175 | $30,372 | $92,247 |
|---|
| 12.00% | $11,200 | $31,058 | $96,463 |
|---|
| 12.25% | $11,225 | $31,759 | $100,862 |
|---|
| 12.50% | $11,250 | $32,473 | $105,451 |
|---|
| 12.75% | $11,275 | $33,202 | $110,238 |
|---|
| 13.00% | $11,300 | $33,946 | $115,231 |
|---|
| 13.25% | $11,325 | $34,704 | $120,438 |
|---|
| 13.50% | $11,350 | $35,478 | $125,869 |
|---|
| 13.75% | $11,375 | $36,267 | $131,531 |
|---|
| 14.00% | $11,400 | $37,072 | $137,435 |
|---|
| 14.25% | $11,425 | $37,893 | $143,590 |
|---|
| 14.50% | $11,450 | $38,731 | $150,006 |
|---|
| 14.75% | $11,475 | $39,585 | $156,695 |
|---|
| 15.00% | $11,500 | $40,456 | $163,665 |
|---|
Member FDIC
- 3.20% APY
- $100 minimum opening deposit
- No monthly service fees
How Simple Interest Works
Put simply, simple interest is the interest paid on the principal you initially deposit. The above formula calculates simple interest.
Some specific accounts, like certificates of deposit (CDs) with specific brokers, pay a simple interest rate. However, when you're considering where to stash your money, consider an account that pays you in compound interest instead.
Below we discuss why compound interest is the way to go.
How Compound Interest Works
With most savings accounts, the interest you earn isn't just on the money you initially deposit. Most savings accounts use compound interest. Basically, you earn interest on the interest that you earned the previous month or day, in addition to the interest you earn on your principal.
For example, let's say you deposit $1,000 into your savings account in January and earn 1% in interest each month. By February, you'd have $1,010. In March, you'd then earn 1% on $1,010, giving you $1,010.10. The power of compounding interest is that the money grows at an exponential rate.
Member FDIC
With 6 month boost, you earn:
| Tier |
Boost APY |
| Balance over $5,000 |
4.25%* |
| Balance less than $5,000 |
0.75%* |
After boost is completed, you will continue to earn our best standard rates:
| Tier |
APY |
| Balance over $5,000 |
3.75%1 |
| Balance less than $5,000 |
0.25%1 |
- Needs to use promo code to qualify: Boost50
- Boost lasts 6 months over standard APY
- Tiered account
- $100 minimum account opening
- Member FDIC
- No Monthly Service fees
- No account opening fees
Expires 12/15/2026
DisclosuresPlatinum Savings is a tiered interest rate account. Interest is paid on the entire account balance based on the interest rate and APY in effect that day for the balance tier associated with the end-of-day account balance. APYs — Annual Percentage Yields are accurate as of January 9, 2026: 0.25% APY on balances of $0.01 to $4,999.99; 3.75% APY on balances of $5,000.00 or more. Interest Rates for the Platinum Savings account are variable and may change at any time without notice. The minimum to open a Platinum Savings account is $100.
This is a limited time offer available to New and Existing customers who meet the Platinum Savings APY Boost promotion criteria.
Accounts enrolled in the Platinum Savings Annual Percentage Yield (APY) Boost promotion will receive a 0.50% APY boost on the Platinum Savings current standard APY tiers for 6 months following the opening of a new account or when an existing Platinum Savings account is enrolled in the promotion. The Platinum Savings APY boost will be applied on account balances up to $9,999,999.00. Account balances above $9,999,999.00 will earn the standard APY. If the standard-published APY should change during the promotion period, the APY boost will move with it, offering an account APY above the standard rate.
The Promotion begins on September 29, 2026, and ends December 15, 2026. Customers enrolled in the promotion prior to the end date will receive the APY boost for the 6-month period outlined in the terms and conditions.
The promotion can end at any time without notice.
New CIT Bank Customers: This Platinum Savings APY Boost promotion offer is valid for New CIT Bank customers, who, at account opening, do not have a valid CIT Bank User ID (a "New Customer") or any open CIT Bank accounts provided that the following requirements are met:
- New customers must open a Platinum Savings account with a valid Promo Code, Boost50. The Platinum Savings APY Boost Promo Code will appear on the online account opening enrollment web page. The Promo Code must be used at the time of account opening. Accounts opened during the program period without the Promo Code are ineligible to receive the APY boost.
- The enrolled Platinum Savings account must be open to receive the APY boost during the promotional period.
CIT Bank Customers with an account prior to the promotion: This Platinum Savings APY Boost promotion is valid for a Primary account owner with an existing account with a CIT Bank User ID before the start of the promotion, provided that the following requirements are met:
- Customers without a Platinum Savings account open prior to the Promotion must open a new Platinum Savings account via the enrollment web page using Promo Code Boost50.
- Customers with a Platinum Savings account opened prior to the promotion may enroll their current Platinum Savings account into the Platinum Savings Boost promotion via the enrollment web page using Promo Code Boost50.
- Customers who are not the Primary account owner on a Platinum Savings account may open a new Platinum Savings account as the primary account owner via the enrollment web page using Promo Code Boost50.
- Accounts opened or enrolled during the program period without the Promo Code are ineligible to receive the APY boost.
There is a limit of one Platinum Savings APY Boost promotional offer per account and per Primary customer. If multiple Platinum Savings accounts are opened, only one account per primary account owner is eligible.
There is no minimum account balance requirement to participate in the Platinum Savings APY Boost promotion.
Additional Important Terms
- The Platinum Savings APY Boost promotion may not be combined with other promotions.
- Customers are ineligible to participate in the Platinum Savings APY Boost promotion if:
- They are earning an APY over the standard rate.
- They participated in a previous APY Boost promotion.
- They participated in a cash bonus promotion in the past 6 months.
- Custodial accounts and accounts in the name of a Trust are not eligible.
- This offer is non-transferable.
The value of Platinum Saving Boost will be reported as interest income on IRS Form 1099-INT for the calendar year in which it was paid. The recipient is responsible for any applicable taxes.
For complete list of account details and fees, see our Personal Account disclosures.
Ben Franklin's Compounding Interest Experiment
When Benjamin Franklin passed away, he famously left the city of Philadelphia and the city of Boston $4,400 each in his will. The money was placed in a trust that was required to sit idle for a period of time before it was utilized. Why? Franklin wanted to harness the power of compounding interest to maximize the funds before the cities could put it to good use.
By 1990, the value of those $4,400 investments had ballooned to $6.5 million!
What is APY?
When researching savings accounts, you may notice that banks list the annual percentage yield (APY). While similar to the interest rate, the APY is different in that it factors in compounding interest. The APY takes into consideration how often your bank compounds interest, whether it be quarterly, monthly, or even daily. The APY, therefore, gives you a more accurate idea of how much interest you will earn than just the flat interest rate.
Savings Accounts
As you might expect, one of the most important things to consider when choosing a savings account is the interest rate and APY. Some online-only banks offer interest rates 10x higher than the national average.
In addition to the interest rate, you'll also want to be mindful of any fees the bank charges and special features they offer. Below we've rounded up some of the best savings accounts available today.
Member FDIC
Expires 12/15/2026
With 6 month boost, you earn:
| Tier |
Boost APY |
| Balance over $5,000 |
4.25%* |
| Balance less than $5,000 |
0.75%* |
After boost is completed, you will continue to earn our best standard rates:
| Tier |
APY |
| Balance over $5,000 |
3.75%1 |
| Balance less than $5,000 |
0.25%1 |
- Needs to use promo code to qualify: Boost50
- Boost lasts 6 months over standard APY
- Tiered account
- $100 minimum account opening
- Member FDIC
- No Monthly Service fees
- No account opening fees
DisclosuresPlatinum Savings is a tiered interest rate account. Interest is paid on the entire account balance based on the interest rate and APY in effect that day for the balance tier associated with the end-of-day account balance. APYs — Annual Percentage Yields are accurate as of January 9, 2026: 0.25% APY on balances of $0.01 to $4,999.99; 3.75% APY on balances of $5,000.00 or more. Interest Rates for the Platinum Savings account are variable and may change at any time without notice. The minimum to open a Platinum Savings account is $100.
This is a limited time offer available to New and Existing customers who meet the Platinum Savings APY Boost promotion criteria.
Accounts enrolled in the Platinum Savings Annual Percentage Yield (APY) Boost promotion will receive a 0.50% APY boost on the Platinum Savings current standard APY tiers for 6 months following the opening of a new account or when an existing Platinum Savings account is enrolled in the promotion. The Platinum Savings APY boost will be applied on account balances up to $9,999,999.00. Account balances above $9,999,999.00 will earn the standard APY. If the standard-published APY should change during the promotion period, the APY boost will move with it, offering an account APY above the standard rate.
The Promotion begins on September 29, 2026, and ends December 15, 2026. Customers enrolled in the promotion prior to the end date will receive the APY boost for the 6-month period outlined in the terms and conditions.
The promotion can end at any time without notice.
New CIT Bank Customers: This Platinum Savings APY Boost promotion offer is valid for New CIT Bank customers, who, at account opening, do not have a valid CIT Bank User ID (a "New Customer") or any open CIT Bank accounts provided that the following requirements are met:
- New customers must open a Platinum Savings account with a valid Promo Code, Boost50. The Platinum Savings APY Boost Promo Code will appear on the online account opening enrollment web page. The Promo Code must be used at the time of account opening. Accounts opened during the program period without the Promo Code are ineligible to receive the APY boost.
- The enrolled Platinum Savings account must be open to receive the APY boost during the promotional period.
CIT Bank Customers with an account prior to the promotion: This Platinum Savings APY Boost promotion is valid for a Primary account owner with an existing account with a CIT Bank User ID before the start of the promotion, provided that the following requirements are met:
- Customers without a Platinum Savings account open prior to the Promotion must open a new Platinum Savings account via the enrollment web page using Promo Code Boost50.
- Customers with a Platinum Savings account opened prior to the promotion may enroll their current Platinum Savings account into the Platinum Savings Boost promotion via the enrollment web page using Promo Code Boost50.
- Customers who are not the Primary account owner on a Platinum Savings account may open a new Platinum Savings account as the primary account owner via the enrollment web page using Promo Code Boost50.
- Accounts opened or enrolled during the program period without the Promo Code are ineligible to receive the APY boost.
There is a limit of one Platinum Savings APY Boost promotional offer per account and per Primary customer. If multiple Platinum Savings accounts are opened, only one account per primary account owner is eligible.
There is no minimum account balance requirement to participate in the Platinum Savings APY Boost promotion.
Additional Important Terms
- The Platinum Savings APY Boost promotion may not be combined with other promotions.
- Customers are ineligible to participate in the Platinum Savings APY Boost promotion if:
- They are earning an APY over the standard rate.
- They participated in a previous APY Boost promotion.
- They participated in a cash bonus promotion in the past 6 months.
- Custodial accounts and accounts in the name of a Trust are not eligible.
- This offer is non-transferable.
The value of Platinum Saving Boost will be reported as interest income on IRS Form 1099-INT for the calendar year in which it was paid. The recipient is responsible for any applicable taxes.
For complete list of account details and fees, see our Personal Account disclosures.
Member FDIC
- $100 minimum opening deposit
- No monthly maintenance fee
- Member FDIC
DisclosuresAPY — Annual Percentage Yield is accurate as of July 1, 2026. Interest Rates for the Savings Connect Account are variable and may change at any time without notice. The minimum to open a Savings Connect account is $100. Fees could reduce earnings on the account.
For complete list of account details and fees, see our Personal Account disclosures.
Member FDIC
- 3.20% APY
- $100 minimum opening deposit
- No monthly service fees
Member FDIC
- Earn 4.00% APY
- No minimum balance requirement
- No monthly service fee
Member FDIC
- Earn 2.75% APY
- No minimum balance requirement
- No monthly service fee
- 4.00% bonus on up to $6,000 balance if you receive and maintain a qualifying direct deposit of $200 or more in a rolling 35 day period. (Otherwise, 0.25%)
- Simply add money to your Savings Pods and enable the Boost feature.
- Earn bonus on up to 3 Savings Pods, up to $2,000 balance each.
- Bonuses accumulate daily.
Current is a financial technology company, not a bank. Banking services provided by Choice Financial Group, Member FDIC, and Cross River Bank, Member FDIC.
- 3.30% APY
- $0 monthly fee
- Withdraw up to $100k per day
Funds placed in the Empower Personal Cash Program are FDIC insured by program banks up to an aggregate of $5,000,000. (up to $10 million for joint accounts)
What's a good interest rate for a savings account?
Many online-only savings accounts pay anywhere from 1.5 to 2.0%. Brick-and-mortar banks usually only offer interest rates as low as 0.03%. When evaluating a savings account, it's important to find a bank with a high interest rate but that also meets your banking needs.
Bottom Line
Savings accounts play an important role in your financial health. Using the power of interest, you have the opportunity to see your account balance grow in a savings account. Combined with regular deposits, a savings account with a good interest rate will set you up for financial success.
Note: This website is made possible through financial relationships with some of the products and services mentioned on this site. We may receive compensation if you shop through links in our content. You do not have to use our links, but you help support CreditDonkey if you do.